The South African property market, and why Cape Town keeps setting the pace
10 September 2026 · 7 min
South African residential property has moved into a firmer phase. The FNB House Price Index accelerated to 4.5% year on year in August 2026, the fastest annual growth in more than three years, and the fourth consecutive month of acceleration. FNB's 2026 outlook puts nominal house price inflation in a 3.5% to 4.5% band for the year, ahead of its 3.1% inflation forecast, which means modest real growth rather than a boom.
Underneath that national average sits a market that is not moving at one speed. One province has pulled away from the rest for the better part of a decade, and one city inside it now carries most of the country's premium residential demand.
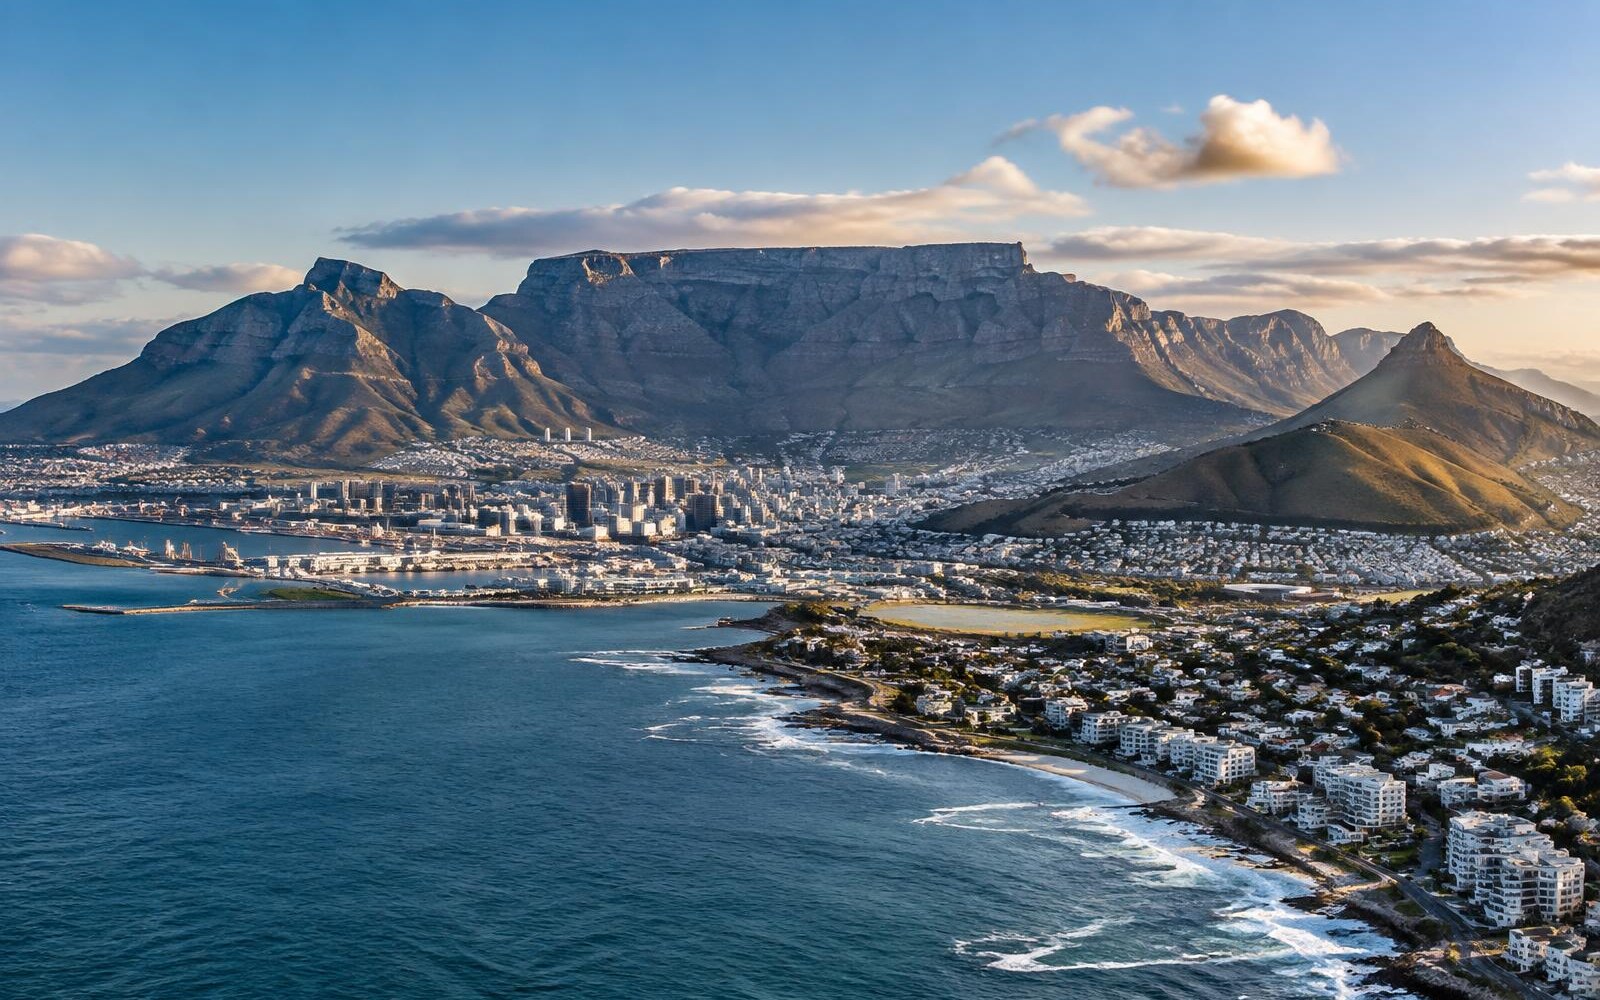
Cape Town's coastline, City Bowl and harbour beneath Table Mountain.
Image: Venture A
The Western Cape has outrun the country
The clearest way to see the divergence is to index house prices to January 2010 and follow them forward. On Lightstone's index, Western Cape house prices are up 179.6% since that point, against 79.7% in Gauteng and 76.7% in KwaZulu-Natal. The gap opened after 2018 and widened sharply through the Covid period.
Figure
House price growth by province, January 2010 to September 2025
Cumulative change in the house price index, January 2010 = 100.
The demand behind that line is largely domestic. Stats SA's 2025 Mid-Year Population Estimates project the Western Cape will receive 500,347 in-migrants across 2021 to 2026, a net gain of roughly 319,000 people. Lightstone tracking cited in the same analysis shows the province's share of total semigration rising from 31% in 2020 to 46% in 2023. In the Wise Move 2025 Migration Report, the Gauteng to Western Cape corridor alone accounted for 48% of every interprovincial move recorded, and the Western Cape retained more of its own residents than any other province.
The same report shows the trend maturing rather than accelerating without limit. About 25% of Western Cape out-migration now flows back to Gauteng or to Gqeberha, driven by employment, return-to-office policies and the affordability gap that the inward move itself created.
How quickly Cape Town stock actually sells
Price growth is one signal. Time on market is the harder one to argue with, because it measures how long a seller waits for an acceptable offer. Lightstone's August 2026 comparison of Johannesburg and Cape Town found a national average of about 10 weeks and six days in the second quarter of 2026, down from roughly 12 weeks and one day a year earlier and still below the long-run average of about 13 weeks.
Figure
Median time on market, homes under R500,000, Q1 2026
Median days a listing stayed active before sale.
The pattern holds further up the market. In the R1.5 million to R2 million band, Cape Town sellers waited a median of 16 days in the first quarter of 2026. In the R3 million to R4 million band, Cape Town's median has fallen steadily from 48 days in the first quarter of 2024 to 20 days in the first quarter of 2026, while Johannesburg's has moved sideways with seasonal spikes.
The exception is the top end. Homes above R6 million were the slowest to sell in Cape Town at a median of 49 days, and 20% of sellers in that band reduced their asking price, with the average reduction at 9.3%. Lightstone reads this as sellers listing aggressively into strong demand and then negotiating.
The holiday side of the market
Cape Town's second demand engine is the visitor economy, and it feeds directly into buying decisions for holiday homes and short-let investment. Cape Town Tourism recorded R24.5 billion in direct tourism spend for 2025, with international arrivals growing. Its destination data puts the United Kingdom at 210,932 arrivals for the year, up 17%, the United States at 167,053, Germany at 161,271 and France at 68,348, the last up 66% year on year.
That traffic supports one of the deepest short-term rental markets on the continent. AirDNA counted 30,814 active short-term rental listings in Cape Town in its August 2026 update, with average annual revenue of about $16,400 per listing, 61% average occupancy and an average daily rate of $168. Airbtics, using a different sample and methodology, reports R451,000 average annual revenue and 71% occupancy as at January 2026. The two providers differ, which is worth knowing before either number is used in a purchase model.
The other major cities
- —Johannesburg, the economic centre and the country's largest city, where residential price growth has lagged the national average and stock in the affordable band sat a median of 132 days on the market in early 2026
- —Pretoria, seat of the executive and the administrative capital, where Stats SA's index has shown freehold property growth running ahead of Johannesburg over a five-year view
- —Durban, the busiest container port in sub-Saharan Africa and the anchor of the KwaZulu-Natal coastal market, where price growth since 2010 has tracked close to Gauteng rather than the Western Cape
- —Gqeberha, a manufacturing and automotive hub on the Eastern Cape coast, now appearing in migration data as a return destination for households leaving the Western Cape on affordability grounds
- —Ekurhuleni, the logistics and aviation belt east of Johannesburg, which has been outperforming the rest of Gauteng on residential building activity
- —Bloemfontein, the judicial capital and central node for the Free State agricultural economy, a smaller and steadier market than the coastal metros
Read together, the data describes a two-track national market. Rates are easing, inflation is anchored near 3%, and activity is recovering across the country, which lifts every metro to some degree. Cape Town sits on top of that cycle with an additional layer of domestic migration and foreign visitor demand that no other South African city currently matches, and with the affordability pressure that comes with it.
Sources and further reading
- FNB, Housing Market Outlook: Entering a new cycle in 2026, 10 February 2026
- FNB Property Barometer, House Price Index 4.5% y/y, August 2026
- Lightstone, A tale of two cities, time on market in Johannesburg and Cape Town, 27 August 2026
- Cape Town Data, Western Cape Semigration: The Data 2020 to 2026, May 2026
- Statistics South Africa, Residential Property Price Index, January 2026 statistical release (P0160)
- Statistics South Africa, Residential property price inflation on an upward trend, provincial and metro breakdown
- Cape Town Tourism, Cape Town's Visitor Economy Holds Its Ground in 2025, June 2026
- Cape Town Tourism, Destination Intelligence, international arrivals by source market
- AirDNA, Cape Town short-term rental market data, updated 5 August 2026
- Airbtics, Cape Town Airbnb data 2026, revenue and occupancy
- Seeff Property Group, Cape Town market update and key shifts ahead, 24 April 2026